About
Location :
Added by Jopie, at 28 July 2017
Opening Hours
- Monday 9:00 AM – 5:00 PM
- Tuesday 9:00 AM – 5:00 PM
- Wednesday 9:00 AM – 5:00 PM
- Thursday 9:00 AM – 5:00 PM
- Friday 9:00 AM – 5:00 PM
- Saturday Closed
- Sunday Closed
Gallery
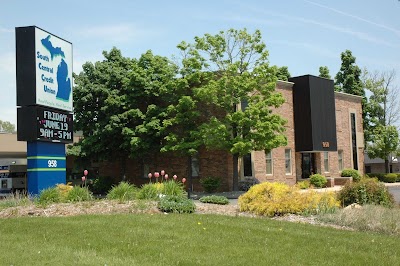

Add missing information
2 Reviews
-
13 August 2017
PAGE 2 OF 3
I asked both him and Caleb when they could have this completed by and I was told to come back Wednesday at 4 PM and they would have it all set. When I left the credit union that day, I called about 5 minutes later to speak to Eric, THE VP, and wanted to know if my GAP insurance would transfer to my new loan. He told me he was not sure but he would call me back. I also asked him since I was mandated to take $1K out on the refi if I could just take $2K, he said yeah they could do that for me. I never received a call back from Eric on the GAP coverage or the ability to transfer it. Wednesday morning I called the credit union to make sure we were still on for 4 PM and was told yes we were. At 2:31PM I Was called by Caleb Kohn and was told now they decided that they weren't interested in doing my second refi. Now I Was extremely confused because we had already confirmed our appt for 90 minutes later. Once I arrived at the credit union I spoke to both Caleb and Eric one on one. They both acted very smug and said they were denying my loans because "they could". I advised them that if I meet their underwriting guidelines they can't just deny a loan that they had already agreed upon and confirmed the appt for. They said their decision was final. I went on to ask them why and they didn't have an answer for me. I was extremely confused and this is why:
My Credit was 657 when they pulled it on 7/31.
I make over $5500 per month just in my base salary(PLUS $4K-$12K a quarter in bonuses)
That makes my allowable debt load $2430 (45% of $5500)
My debts on my credit report are in the amounts of $420, $486, $160, and they include my cc with them that has a 10K limit at a rate of 4% in case I were to max it out. 10K at 4% equals $400 per month. My total debts are $1766 per month IF MY CC WERE MAXED OUT.
My credit report shows 422/422 payments made on time. NEVER MISSED A PAYMENT IN MY LIFE.
Now mind you refinancing my vehicles was even decreasing my debt load by $135 per month between the two loans. So when Eric Samon said it had something to do with my DTI I was even more confused. I don't think he is used to someone putting him on the spot or knowing anything about the finance world.
Once I brought up the possibility of my lawyer getting involved since I had spoke to him on my way there, they immediately got even more upset. Once they found out I had recorded all conversations with them they were even more upset and unwilling to do anything. Which that part I could understand because they were recorded in admitting that they pulled my credit without consent and they were recorded promising me everything under the sun and then going back on the deal last minute because "THEY CAN".
I asked to speak to the CEO, Terri Papiersky. They denied me that right for about 30 minutes. Finally they got her to come out of her "throne" and she shook my hand and told me she wasn't interested in hearing what I had to say. Now this was very upsetting. For a CEO of a credit union to act as unprofessional as that was the icing on the cake. I joined a credit union so that I was treated fairly and like family. What the Branch Manager (Caleb Khon), VP (Eric Samon), and CEO (Terri Papiersky) did is unacceptable. You do not treat people this way nor do you carry out your day to day business this way.response / report this review -
04 August 2017
PAGE 1 OF 3
When I very first joined this credit union I was amazed at how well I was treated by the Branch Manager Caleb Khon. He was reluctant to get my car loan processed in a way I had never seen before. He told me all about how he did over $2.5M in loans the month prior and made over $15K in commission and that the board of directors was currently restructuring his pay plan so he couldn't make as much money. Went on to tell me how his base salary is $50K a year and with his bonuses he should clear $200K. He pulled my credit, wrote the loan, and disbursed me the funds within 30 minutes. I have been in banking for over 3 years and have never seen such a magical event. While closing the loan I spoke with Caleb about bringing my other loan to the credit union so that I could have all of my "ducks" under one roof. At this time he told me absolutely no problem, just to let him know when I was ready. Fast forward 3 months. I go in to finally refinance my second car since I had some free time in my schedule. I sit down with Caleb and he already has my NEW credit report on his desk. I was confused because I never gave him the okay to pull my credit report. Not verbally nor did I ever sign anything dictating he had my consent. I didn't make a huge deal about it at this time because I thought he had my best interest at heart. Once we looked at my new score and realized my score had went up 38 points in 3 months I realized that qualified me for a rate of 3% less on the first car I purchased. I told Caleb I wanted to refinance that vehicle as well, he said no problem. We started to go over the numbers to see what I was qualified for. He told me they would not be able to go above 100% of the NADA value on my second car which I was confused because earlier in a text message he said that he could. However I was not worried because I wasn't negative in equity. So when I left the credit union on Monday the deal was to come back on Tuesday and they would refinance my first loan, 3 months old, to a rate of 3% lower than my original rate and refinance my second car at that same rate with a cash out of about $2500. The catcher was that in order to refinance my first loan I had to take an additional grand out on top of the loan since I just purchased it 3 months prior. I agreed. Tuesday comes and I take the day off work to get my loans closed. I go in to see Caleb and he goes on to tell me how they don't feel comfortable doing the loans the way he had previously stated. So with my finance experience, as I manage a bank as well, I asked the question: why? He could not give me a straight answer, he blamed it on the VP of the credit union. I ask to speak to the VP of the credit union. HE, Eric Samon, comes out and greets me. I ask him why he didn't feel comfortable doing my second loan and his words were "Since you don't have any other products with us, I do not feel comfortable going up to 125% NADA value on the loan". I was in disbelief with what he just told me. I corrected Mr. Samon and let him know that I had one car loan there already that I pay two weeks in advance plus I have a Credit Card with them with a $10K limit on it. He looked stunned and started apologizing for his ignorance. He asked me if I minded him taking a closer look at my numbers and I said no I did not. I waited for 30 minutes for him to do so. Mr. Samon came back out and said he still didn't feel comfortable but he did feel comfortable going to 100% NADA value on my second car and allowing me to refinance my first loan with them at the lower interest rate AS LONG AS I TOOK AN ADDITIONAL GRAND OUT ON THE NEW LOAN.response / report this review